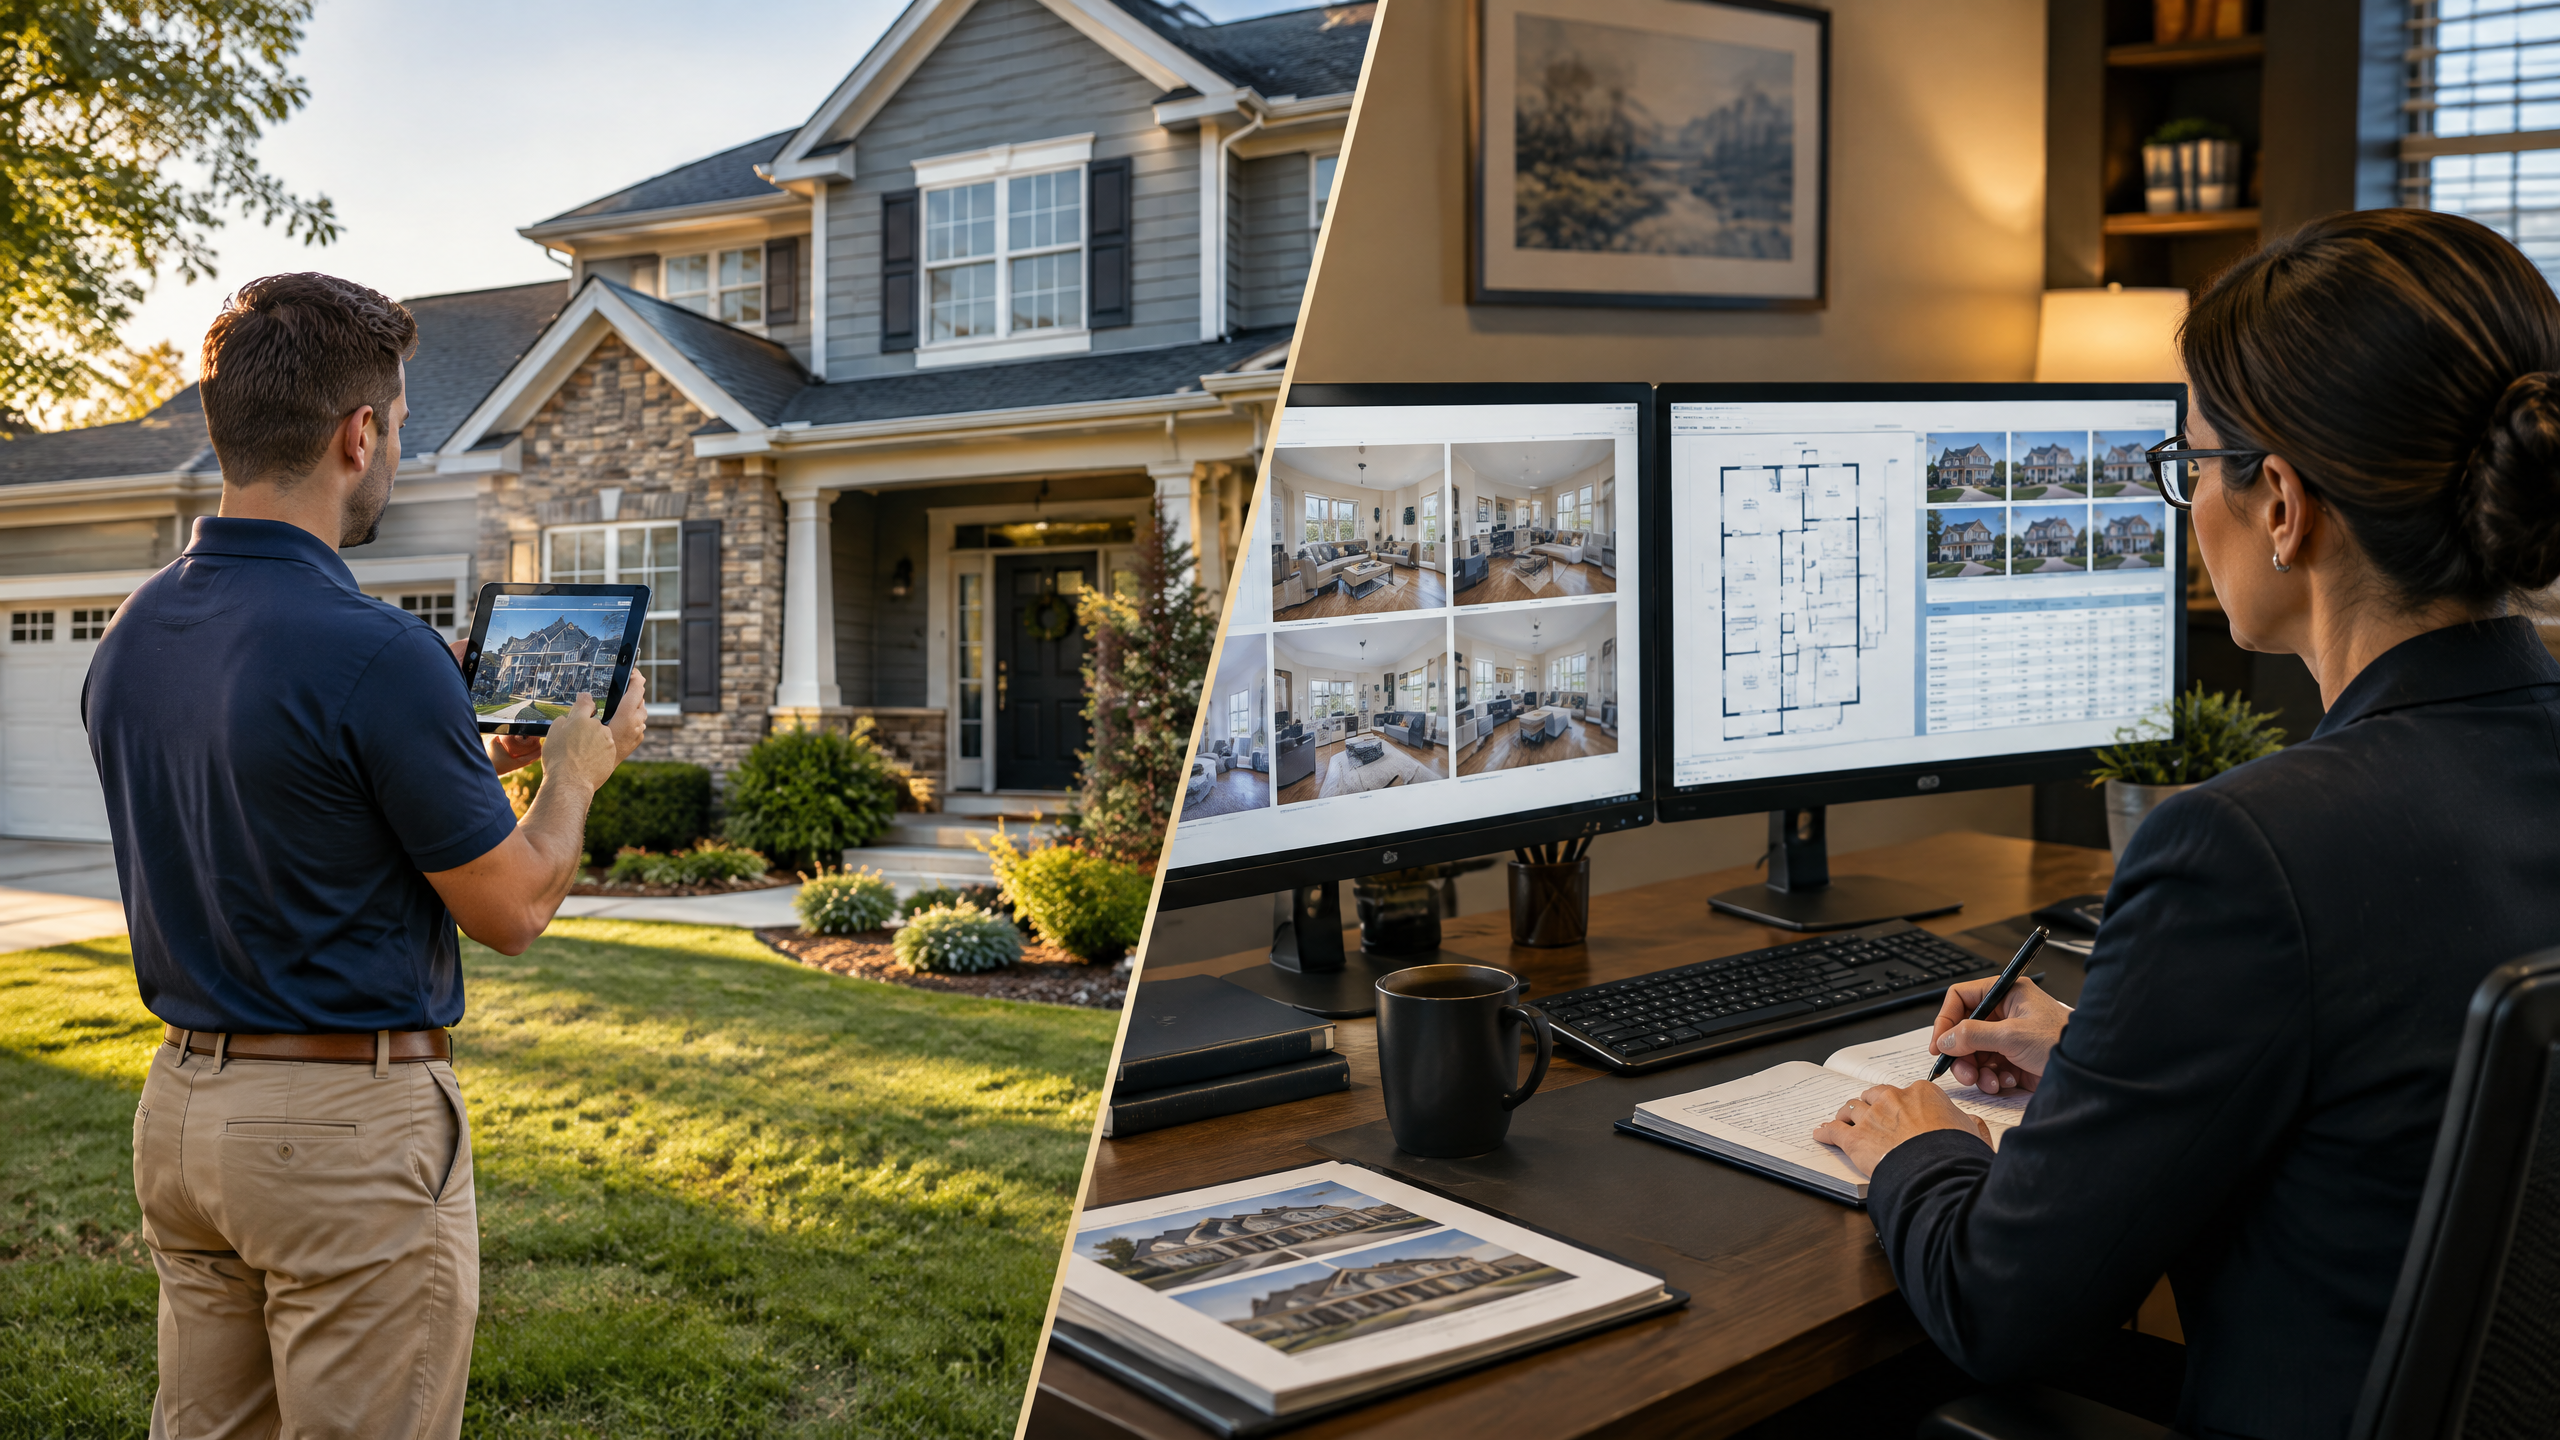
What a hybrid appraisal is, and how to order one before the traditional panel is already late.
A hybrid appraisal is a licensed appraiser’s opinion of value that uses a trained third party’s interior and exterior property data collection. The collector does not value the house. The appraiser does. The effective date is the day that opinion is formed.
The four-step file
STEP 1
Confirm AUS eligibility
The automated underwriting system has to offer the hybrid appraisal. If that message is not there, do not invent a hybrid appraisal to save a day. Eligibility is an investor gate, not an AMC preference.
STEP 2
Collect the house with a trained inspector
A trained, vetted collector captures interior and exterior data, photos, and a measured floor plan. That package is submitted through the investor's required property-data channel and reviewed before the appraiser is expected to stand behind it.
STEP 3
Hand the collection to the appraiser at engagement
If the appraiser did not collect the data, the lender or AMC must share the collection when the assignment starts. Asking the appraiser to value first and read the PDC later is how you get an incomplete scope.
STEP 4
The appraiser writes a hybrid appraisal
The appraiser uses the collection plus other data and delivers a hybrid appraisal. That is the product the AMC or lender ordered. This desk does not also produce a full UAD 3.6 interior on the same assignment.
Near misses that kill files
A hybrid is not a desktop
Someone still walks the property. The walk is a data collection, not an appraisal, but it is physical. If no collection is submitted through the required channel, you do not have a hybrid appraisal.
A hybrid is not an AVM with photos
The value is still a licensed appraiser's opinion. Automation can support the file. It cannot replace the opinion.
A hybrid is not always cheaper enough to be the default
Cost and cycle time usually improve on vanilla one-unit properties. Complex, damaged, or ineligible property types still need a traditional interior. The AUS message is the first filter; property reality is the second.
The collector is not the appraiser
Unless the same person is later engaged as the appraiser, the collector has no value opinion. Mixing those roles without saying so in the report creates a scope problem the lender still owns.
The AMC or lender chooses the product
A hybrid appraisal can stand in for a full UAD 3.6 interior on files that allow it. That is a product choice, not a dual report. If you order hybrid, this firm does not also write a UAD 3.6 appraisal. If you need a full UAD 3.6 interior, order that instead.